Konrad Jakob Mueller

Hi!
I’m Konrad. I’m a PhD student at Imperial College London, supervised by Lukas Gonon, and a part-time quantitative research associate at J.P. Morgan. I am part of the Oxford-Imperial Centre for Doctoral Training in Mathematics of Random Systems.
I am interested in machine learning, quantitative finance, and the intersection of those two fields. My research is focussed on developing efficient and robust techniques for solving stochastic control problems, in particular hedging problems.
news
| Nov, 2026 | I’ll be speaking at QuantMinds 2026 (19 Nov 2026, 11:55) about my latest research on stationary ambiguity. |
|---|---|
| Sep, 2026 | Our paper, Generating Financial Time Series by Matching Random Convolutional Features, has been accepted to NeurIPS 2026! |
| Aug, 2026 | Our new preprint, Robust Control under Stationary Ambiguity, is up on arXiv! This is my favorite project that I have worked on during my PhD so far. It is based on a simple observation/idea, but has lots of practical implications. Check it out! |
| Dec, 2025 | Presented a preliminary version of our paper, Generating Financial Time Series by Matching Random Convolutional Features, at the NeurIPS 2025 Workshop on Generative AI in Finance. |
publications
2026
-
-
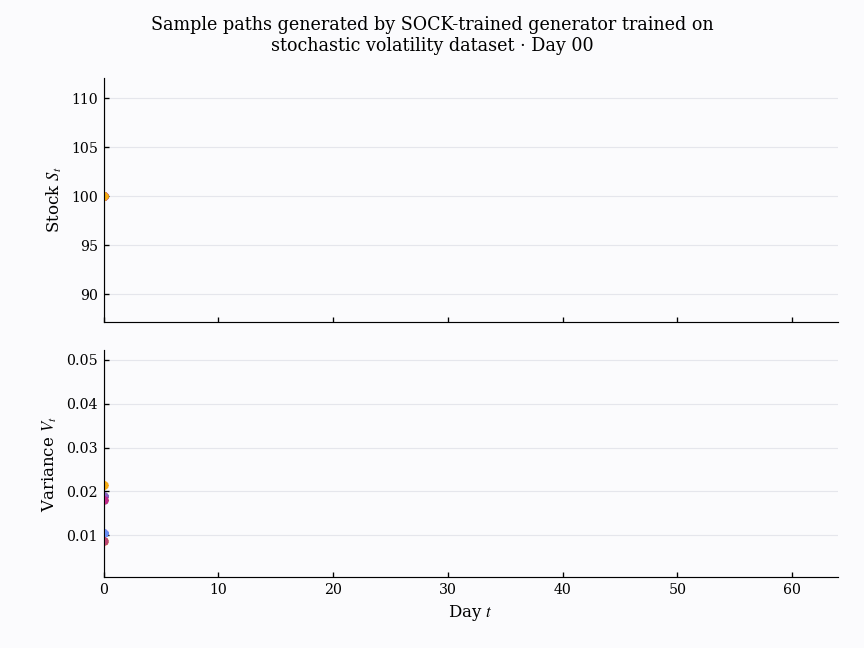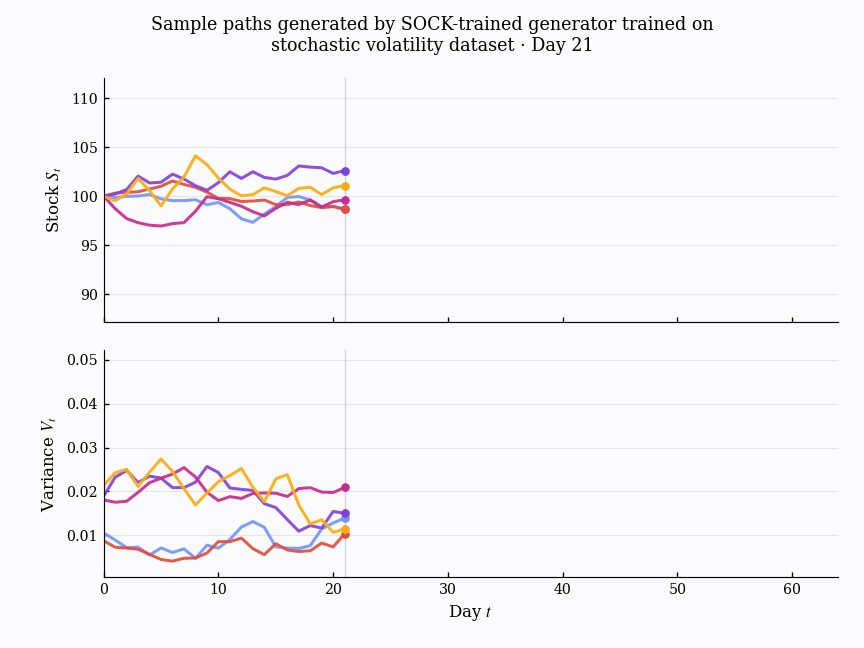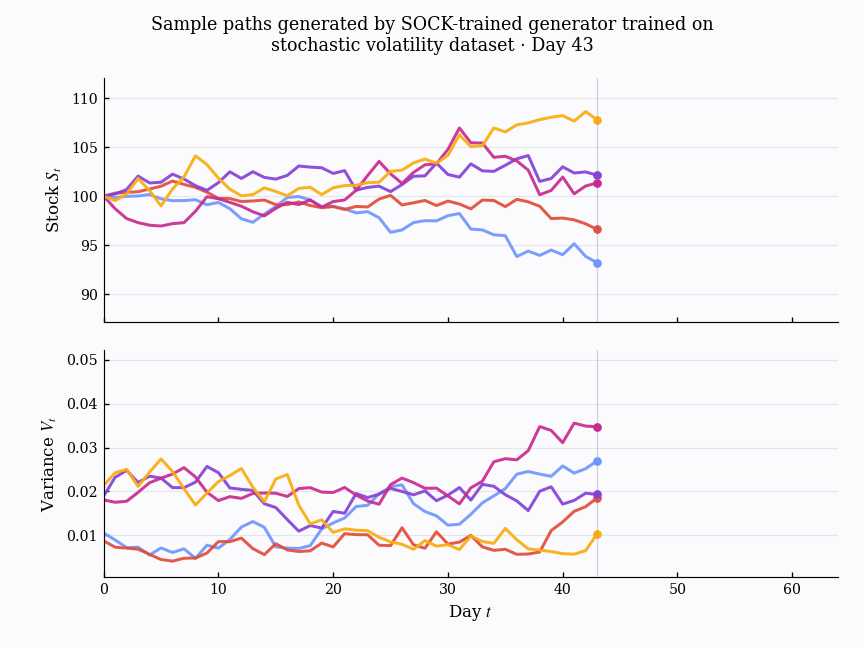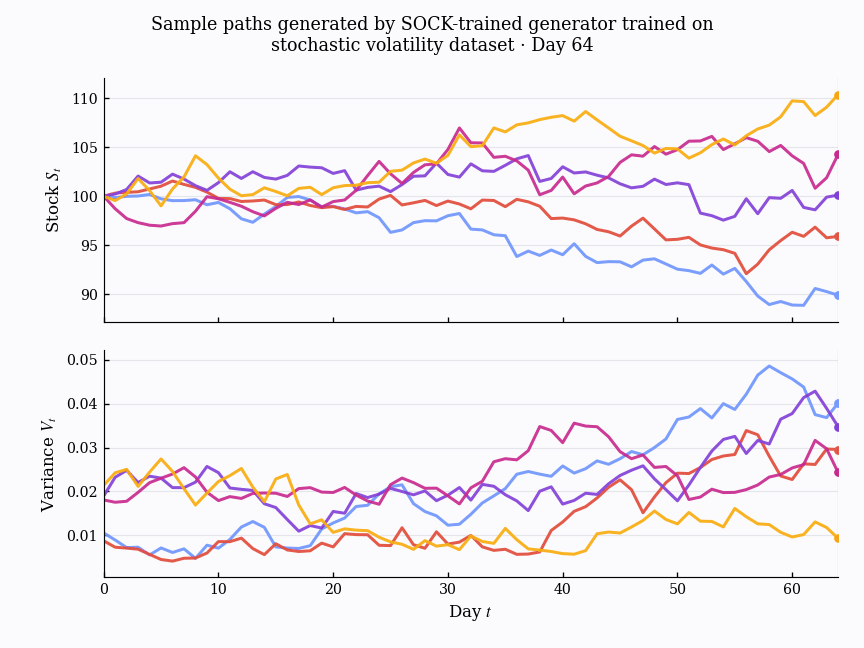 Generating Financial Time Series by Matching Random Convolutional FeaturesArXiv preprint arXiv:2606.05138, Jun 2026